AI Search and the Dark Funnel: What Generative Search Does to B2B Demand Generation
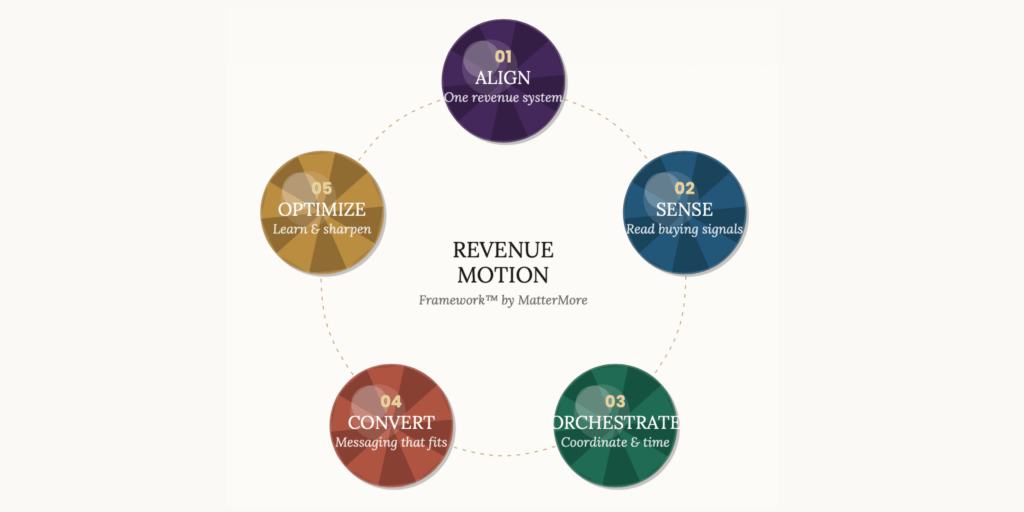
For the full picture of how AI is changing the B2B demand funnel, read Chapter 3 of the Revenue Motion Framework™. This post goes one level deeper: what GEO changes in each phase, and what is still unresolved.
The dark funnel was already mostly invisible
The dark funnel — recap
If you’ve read How Enterprise Buying Actually Works, you know the argument: enterprise B2B buyers do most of their decision-making in places your team will never see. Peer conversations. Internal Slack debates. Analyst calls. Conference hallway conversations. Internal shortlists formed weeks before a single form is filled in.
When the buyer finally raises their hand by submitting a contact form, the decision is mostly already made. The visible part of the funnel is the smaller part. The invisible part — the dark funnel — is where the real evaluation happens.
The Revenue Motion Framework was built around this reality. Phase 2 (Sense) is specifically designed to detect signals of buying activity before the form-fill — third-party intent data, repeat visits from multiple roles, content engagement patterns. The framework doesn’t pretend you can see everything. It just argues that you can see enough to act earlier than the form-fill model lets you.
Or it argued that — until AI search made the dark funnel deeper.
AI search just made the dark funnel darker
The shift
When B2B buyers used to research a category, they typically visited vendor websites at some point in the process. Sometimes anonymously, sometimes signed in, but they were there. Even anonymous visits left behavioural signals — pricing-page visits, content downloads, repeated visits from multiple users at the same domain. That behaviour was the raw material of Phase 2’s Account Interest Rating.
Now ChatGPT, Claude, Gemini, Perplexity and Microsoft Copilot answer the buyer’s questions directly, in conversation. The buyer asks “What are the leading platforms for enterprise observability?” and gets a structured, citation-backed answer without clicking a single vendor link. The vendor research happens in a conversation you never see.
For the seven shifts this causes across the whole demand funnel, see Chapter 3: How AI Is Changing the B2B Demand Funnel. Below, the focus is on what it does to the signals the framework runs on.
The vanishing signal
What this does to demand generation
Most B2B demand generation models — including the Revenue Motion Framework — depend on signals to function. The AIR model in Phase 2 (Sense) reads:
- First-party behaviour on your properties (pricing-page visits, content engagement, multi-role visits)
- Third-party intent data (Bombora, 6sense, ZoomInfo)
- Account-level patterns across multiple sources
AI search erodes the first category — first-party behaviour — by reducing how often buyers visit at all. It doesn’t entirely eliminate it; product-led companies still see significant traffic, and at some stage in the deal the buyer will visit. But the research-stage visits — the ones that used to surface a buyer 60 or 90 days before they raised their hand — are getting absorbed into AI conversations.
The structural consequence: the AIR model has fewer inputs at the moment it most needs them. The signal you needed in Q1 to act in Q2 is now flowing into a Gemini conversation in Q1 and only surfacing on your radar when the buyer finally clicks through in late Q2.
You can solve this with more third-party intent data — but third-party intent only goes so far, and most of it was already noisy. The structural shift is real and not solvable by buying more data.
What changes on the buyer's side
More informed buyers, narrower windows
The other side of the same shift: by the time the buyer arrives on your website, they’re further along the journey than before.
They’ve already asked an AI which platforms are credible in your category. They’ve already gotten a comparison of approaches. They’ve already seen a synthesised position on your strengths and weaknesses — whether the synthesis is accurate or not. They arrive with a formed opinion rather than an open question.
That changes what they want from your website. They’re not looking to be educated. They’re looking for confirmation of an opinion they already hold. They’re looking for the next step in a decision they’ve already mostly made.
Phase 4 (Convert) — the messaging matrix — was built assuming buyers arrive across a wide range of maturity levels and the framework helps the team match the message to where the buyer is. AI search compresses that distribution. Buyers tend to arrive further along than they used to. The matrix still applies — but the team will use it more often at higher maturity levels (D and E) and less often at the educational stages (A and B).
The “demand generation” window has narrowed. The “demand confirmation” window has opened.
Generative Engine Optimization (GEO) — the emerging discipline
GEO, defined
Generative Engine Optimization is the discipline of making sure your perspective is the answer the AI cites when the buyer asks an AI for help in your category.
It’s related to SEO but operates on different principles. Traditional SEO optimises for ranking in a list of links. GEO optimises for being cited in a synthesised answer. Different signals matter:
- Authority and citability. AI search platforms preferentially cite sources they treat as authoritative. Building that authority is part of the work.
- Structured knowledge. Content that’s clearly organised, with explicit claims and supporting evidence, is easier for an AI to extract and cite.
- Comprehensive coverage. AI search rewards depth — sources that explain a topic completely tend to be cited more than thin overviews.
- Update freshness. Synthesised answers favour current sources; stale content tends to get displaced.
- Cross-platform presence. Showing up in multiple authoritative places (your site, industry publications, peer mentions, analyst reports) compounds your citation odds.
GEO is its own work — not just SEO with new platforms. The tools, metrics, and ownership are still settling in the industry. Some teams put it under SEO; some under content; some under demand generation. Most still don’t have an owner at all.
In B2B specifically, GEO is the discipline that determines whether your category-defining ideas (like the Revenue Motion Framework, in MatterMore’s case) get cited when buyers ask AI about your category. Without that visibility, your framework — however good — lives entirely inside your own properties.
Where GEO sits inside the Revenue Motion Framework
GEO and the framework
The honest answer: GEO doesn’t add a sixth phase to the Revenue Motion Framework. The framework is about the operating model of demand generation — alignment, signal, orchestration, conversion, optimisation. GEO is more like AI itself (covered in this post: AI in B2B Demand Generation: Personalisation, Reframed) — an underlying capability that runs across multiple phases and makes each one work better in the AI-search era.
Specifically:
- Phase 1 (Align) — the ICP definition now needs to include where do my buyers actually search? If a meaningful share of your buyers research via Claude, Gemini or Perplexity, that fact belongs in the ICP document. It changes media planning, content investment, and the signal taxonomy.
- Phase 2 (Sense) — the signal stack needs new inputs. Who’s citing us in AI answers? becomes a meaningful signal that didn’t exist three years ago. Tools to monitor AI mentions of your brand and category are emerging (some early-stage, all imperfect). The AIR model will need recalibration as AI-derived signals start contributing meaningful predictive value.
- Phase 3 (Orchestrate) — the play library needs to account for buyers arriving from AI search later in their journey. A “Spotted Opportunity” triggered by an AI-cited content piece is a different account state than one triggered by a pricing-page visit. The development play might be shorter or more validation-focused.
- Phase 4 (Convert) — two shifts. First, the messaging matrix needs to skew toward higher maturity levels (D and E — confirmation and next step), and toward role-specific buying-group concerns rather than education. Buyers who arrive late don’t need to be sold on the category; they need to be helped to confirm and act. Second — and this is the more important shift — the matrix is no longer a content library for owned channels. It’s a content strategy for every channel where the buyer asks for help, including AI search. The same matrix cells — the answers each role at each maturity level is looking for — are also the questions buyers are now asking ChatGPT, Claude, Gemini and Perplexity. The matrix content has to be built as LLM-citable content from day one, not as on-site assets retrofitted for LLMs later. If your CFO-at-maturity-C cell only exists as a deal-stage talking point in the AM’s playbook, the AI conversation the CFO has at the formation stage is being shaped by your competitors’ content, not yours. Personalisation at the confirmation stage on your website is most effective when the same point of view has already been planted in the buyer’s mind during the AI-mediated research phase. Build the matrix once; deploy it on every surface the buyer is asking for help.
- Phase 5 (Optimize) — GEO performance enters the weekly operating meeting as a leading indicator. “Are we being cited more or less in AI answers this month?” becomes a question worth tracking alongside the other operational metrics.
The framework’s structure holds up. Its inputs and outputs recalibrate.
Open questions I don't have answers to yet
What I'm still working on
This post is also an honest admission of what I don’t know yet. Four open questions:
What is the best way to measure GEO? Today, brand-mention tools for AI search are imperfect — they sample, they miss conversations, they don’t relate to audience segments, and the AI platforms themselves don’t expose the underlying telemetry. The metric infrastructure is years behind the practical importance of the discipline.
Can the AIR model meaningfully incorporate AI-derived signals? If a buyer saw a Gemini answer that named your product next to a competitor’s, does that count as a buying signal? How do you weight it against the website signals you already track? I don’t have a confident answer yet.
Does the persona × maturity matrix need a new column for “AI-informed buyer”? Or does it just mean teams will work the existing C/D/E columns more often? My current read is the latter — the matrix structure holds — but I want to see another six months of data before I commit.
How do we balance two very different audiences on our website? On one hand, we need to provide enough educational, structured content for AI platforms and search engines to understand our expertise, solutions and point of view. Large language models increasingly rely on published website content to learn, reference and recommend brands.
On the other hand, human visitors often arrive on a website already informed. They don’t necessarily need long educational content — they need a relevant, engaging and frictionless experience that helps them evaluate options, build confidence and take the next step.
This creates a growing gap. Websites now serve both AI crawlers and human decision-makers. Content that performs well for AI discovery is not always the content that creates the best user experience. Organisations therefore need to find the right balance: publishing enough educational depth to strengthen visibility in AI-powered search, while designing experiences that support informed buyers who want clarity, relevance and action rather than more information.
The question is no longer simply how to optimise for search engines. It is how to architect digital experiences that serve both audiences: AI systems that consume content at scale, and human visitors who expect value within seconds.
These are real open questions. I’m working through them in my SUSE day job, where I’m responsible for SEO and GEO. This post represents the current state of my thinking, not a settled position.
Where to go from here
Two ways to take this further:
→ Read it. The complete Revenue Motion Framework™, second edition, with the 90-Day Action Plan deck. Free, no form. → Download free
→ Work through it together. Want to apply this to your own demand engine? Let’s talk. →
If you’re working on this same problem at your own company, I’d genuinely like to compare notes. The DM is open.